The HECM Line of Credit: The Retirement Safety Net Most Cincinnati Homeowners Have Never Heard Of Meta description: A HECM line of credit can grow over time and can't be frozen or
In 2008, plenty of retirees in Hamilton and Warren Counties did everything right. They saved, they invested, and they kept a home equity line of credit open "just in case."
Then the banks froze those lines.
The safety net disappeared at the exact moment people needed it. After more than 23 years specializing in reverse mortgages, I still think that's one of the most underappreciated lessons in retirement planning. A line of credit is only a safety net if it's there when things go wrong.
That's why I want to talk about a feature of the Lifestyle Home Loan (HECM) that even many financial professionals don't fully understand: the HECM line of credit.
What Is a HECM Line of Credit?
A HECM line of credit is a way for eligible homeowners 62 and older to set aside a portion of their home equity as available funds. They draw on it only when and if they need it. You don't make monthly mortgage payments on what you borrow. The balance is repaid when you sell the home, move out permanently, or pass away. You still need to live in the home as your primary residence and keep up with property taxes, homeowner's insurance, and maintenance.
Three Features That Make It Different From a HELOC
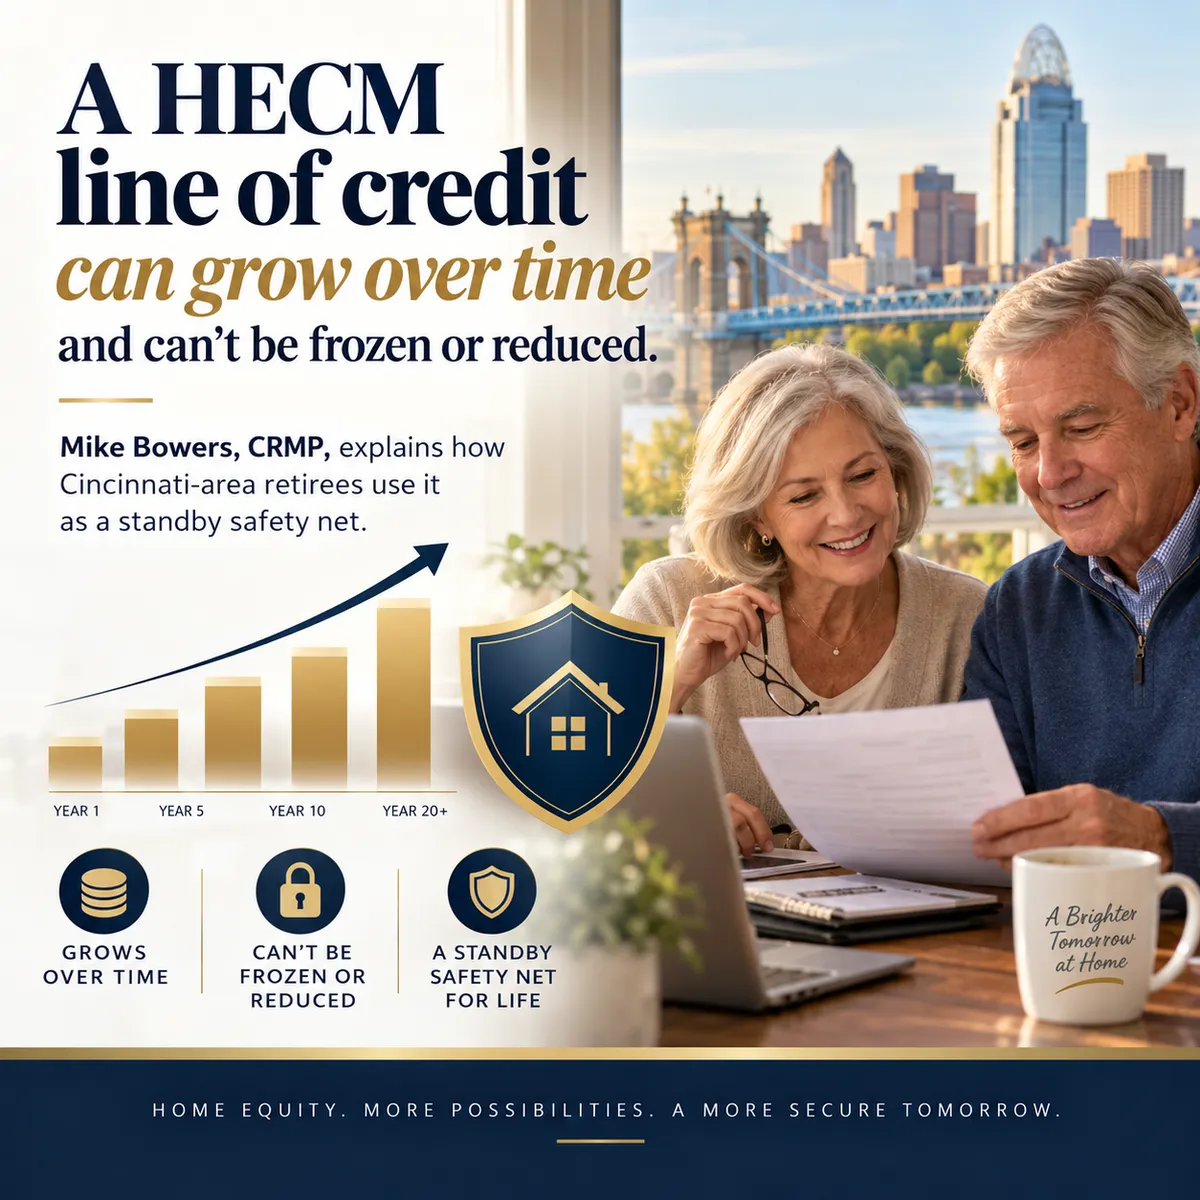
1. The unused portion grows. The available credit on a HECM line increases over time at the same rate as the loan's interest rate plus the annual mortgage insurance premium. Your borrowing power grows whether or not home values rise.
2. It can't be frozen, reduced, or canceled as long as you meet the loan obligations. That's the 2008 problem, solved.
3. There's no monthly payment. A traditional HELOC eventually requires repayment on a schedule. A HECM line of credit doesn't, although voluntary payments are always allowed.
How Retirees in Ohio and Northern Kentucky Use It
I see clients from Mason to Fort Thomas use the line of credit in a few practical ways.
As an emergency fund. A new roof, a furnace in January, or a health event. Retirees don't have to sell investments or tap retirement accounts at a bad time, because they already have funds set aside.
As a buffer against market downturns. One of the biggest risks in retirement is sequence-of-returns risk, which means having to sell investments while the market is down. Some retirees draw from the line of credit in down years and let their portfolio recover. Retirement income researchers have studied this "buffer asset" approach for years.
As a longevity reserve. Opening the line early and leaving it alone gives it the most time to grow. For a homeowner in their 60s, that can mean a significantly larger safety net in their 80s, when costs tend to rise.
Why Timing Matters
The growth feature rewards people who plan ahead. A line of credit opened at 63 and left untouched has many more years to grow than one opened at 78 out of necessity.
I often tell couples in Clermont and Butler Counties that the best time to set up a safety net is before you need one. If you wait until it's an emergency, you'll have fewer options.
Is It Right for Everyone?
No. A HECM has upfront costs, and it's a loan secured by your home. It makes the most sense for homeowners who plan to stay in their home for the long term and want flexibility and liquidity in their plan. The right answer depends on your goals, your other assets, and your family situation. That's what a planning conversation is for.
Frequently Asked Questions
Q: Does a HECM line of credit really grow?
Yes. The unused portion grows at the loan's interest rate plus the annual mortgage insurance premium. The growth applies to your available borrowing capacity. It is not an investment return.
Q: Can the lender freeze my HECM line of credit?
No, as long as you meet the loan obligations. Those include living in the home as your primary residence and paying property taxes, insurance, and maintenance.
Q: Do I have to make monthly payments on a HECM line of credit?
No. Monthly payments aren't required. You can make voluntary payments at any time, and they restore available credit.
Q: Who qualifies for a HECM in Ohio and Kentucky?
Homeowners 62 and older with significant home equity who live in the home as their primary residence. The home must meet FHA standards, and borrowers must complete HUD-approved counseling.
Want to see what your line of credit could look like? Let's sit down over a cup of coffee. Call (513) 680-6168 or email [email protected].
Mike Bowers, CRMP
HECM Housing Wealth Advisor | Mutual of Omaha Mortgage | NMLS# 61535
4555 Lake Forest Dr, Suite 650, Cincinnati, OH 45242
(513) 680-6168 | [email protected] | michaelbowerscrmp.com